Latest from BCA Research
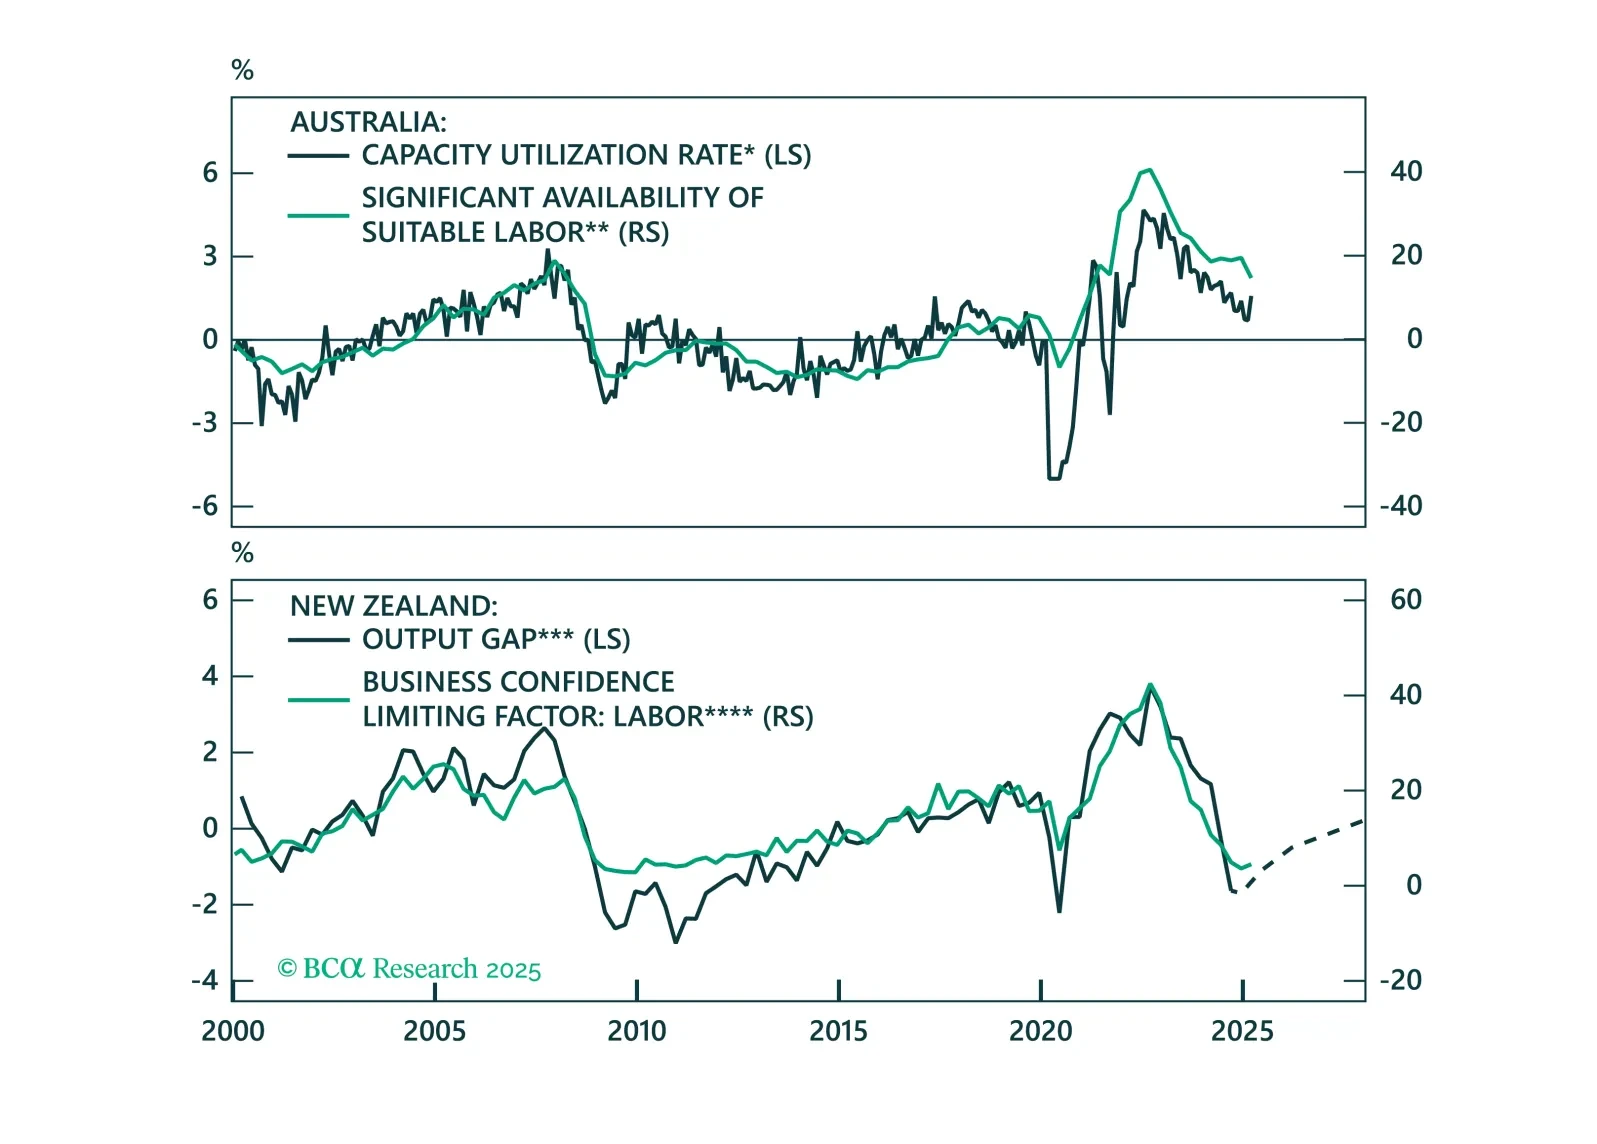

The European economies are facing a major deflationary shock. We recommend that investors stay long a basket of Central European (CE3) domestic bonds. They should also upgrade CE3 bonds and stocks in their respective EM portfolios.


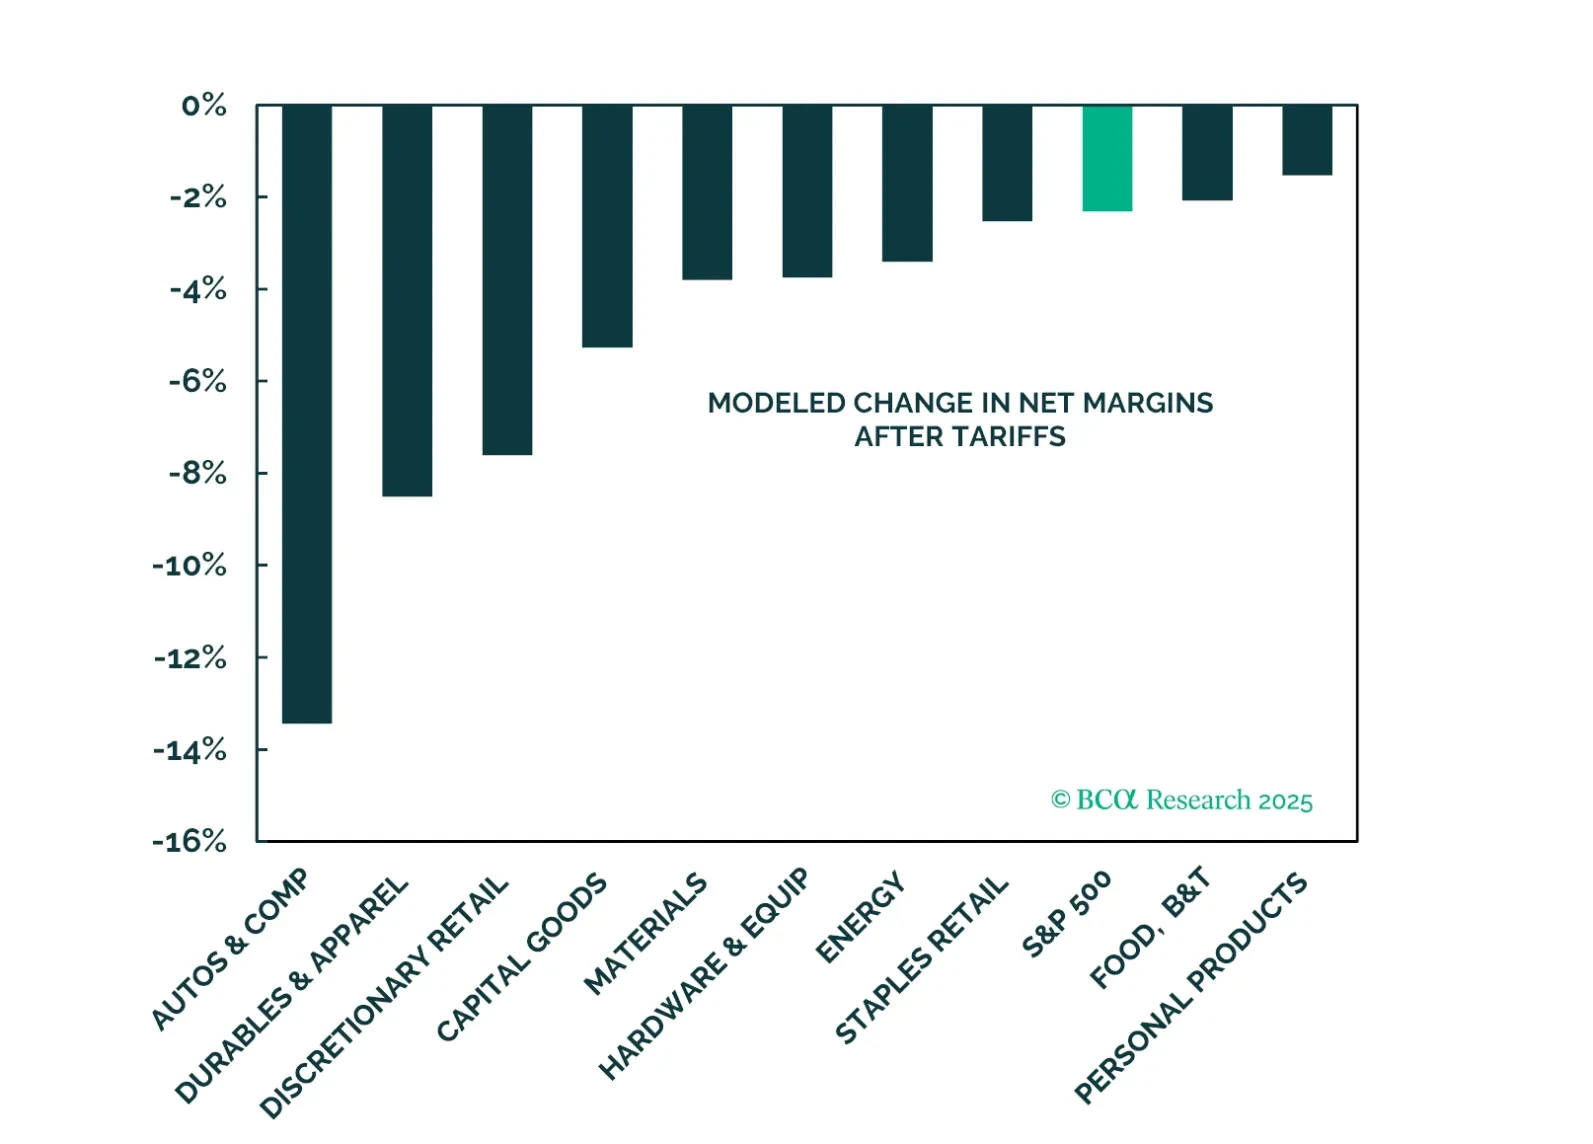
The policy-induced decline in consumer confidence has spread to businesses and investors, increasing the probability of a recession even if the administration reverses field on its aggressive tariff measures. We reiterate our defensive asset allocation recommendations.

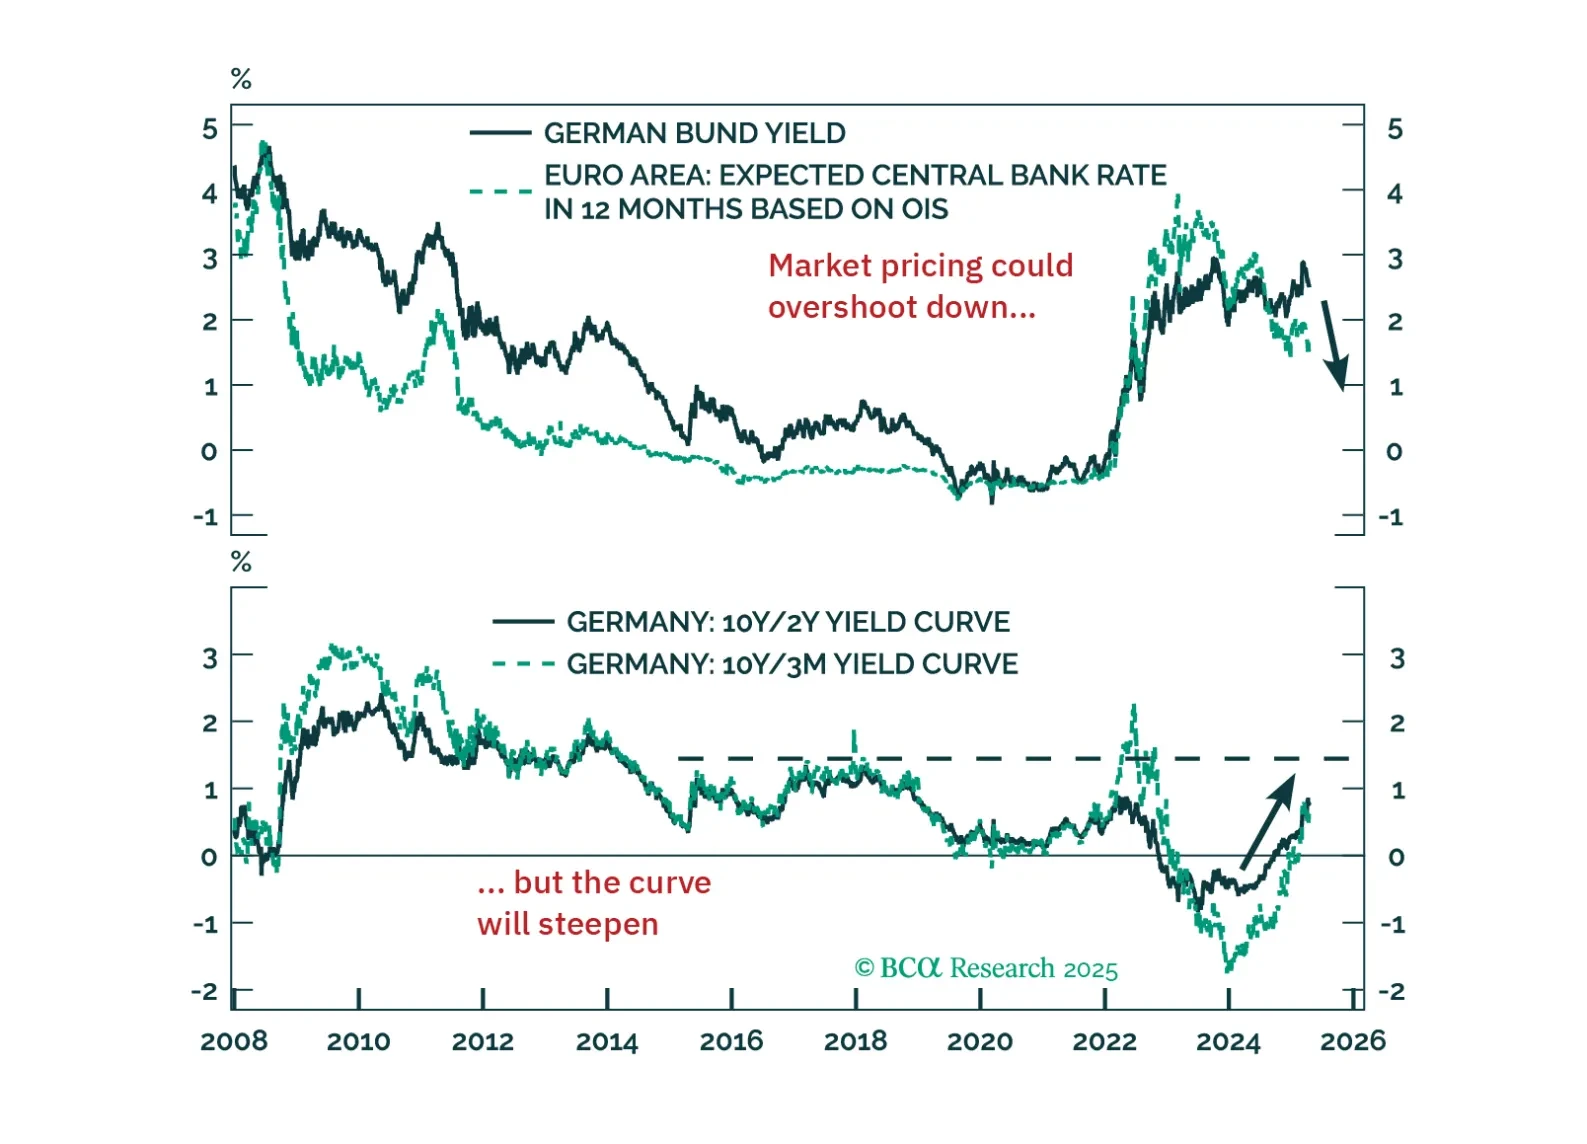
Europe’s deflation problem is getting harder to ignore. This week’s ECB cut is just the beginning — tariffs, the euro’s rally, and softening demand all point to more easing ahead. We explain what it means for yields, equities, and EUR/USD.

This week, our three screeners cover equity plays in: Canadian Consumer Staples, high-beta Swedish equities, and factor plays across global equities.
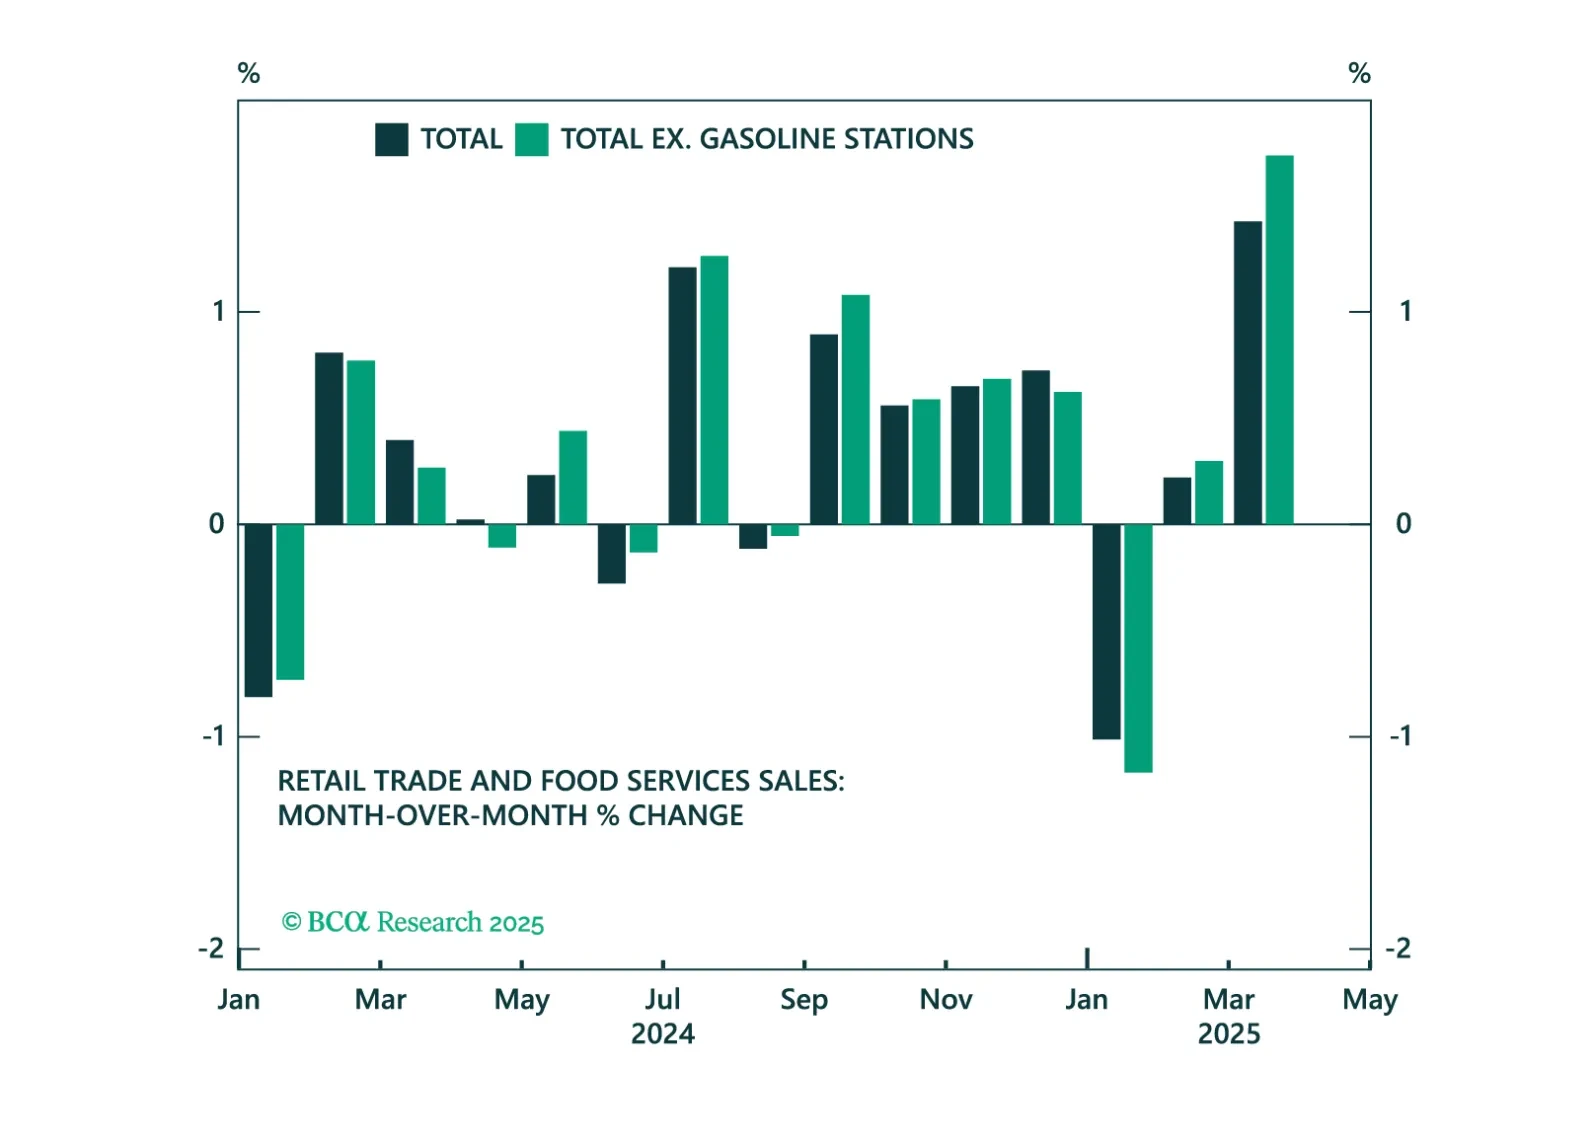
Fed Chair Jay Powell’s remarks yesterday were in-line with our base case expectation that the Fed will not cut rates proactively in the face of rising tariff-driven inflation.
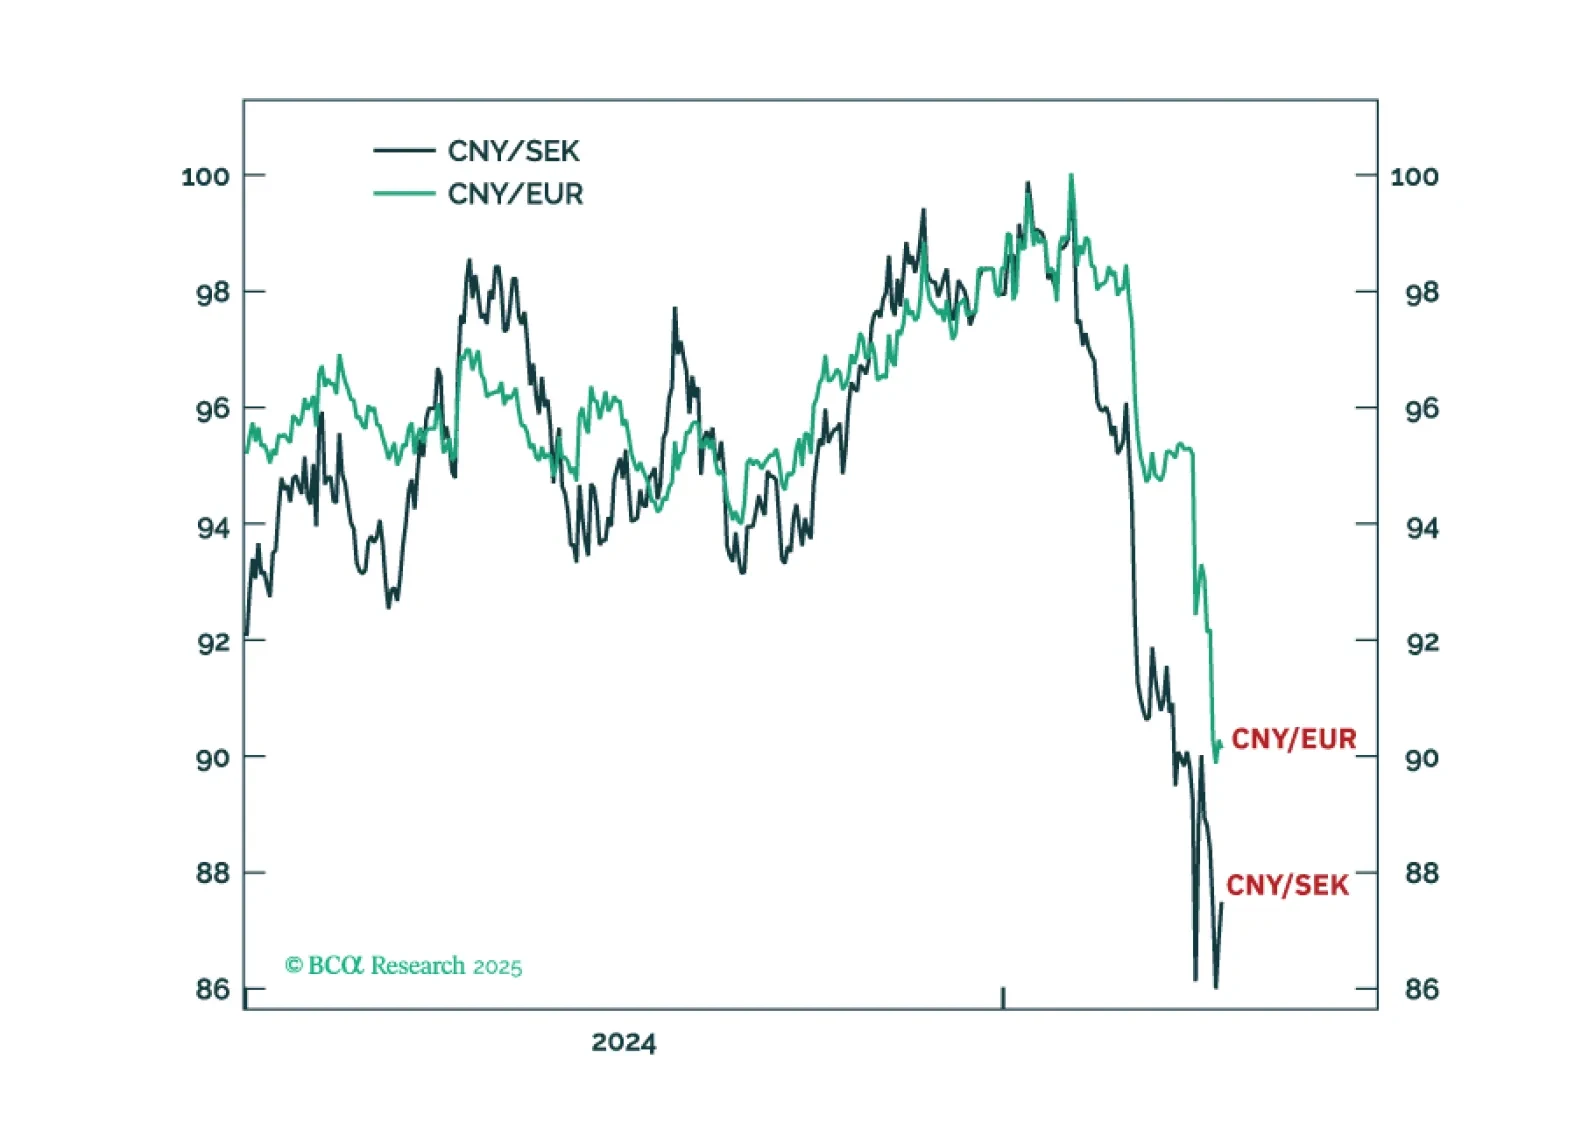
The textbook impact of the world’s largest goods importer, the US, imposing an ultra-high tariff on the world’s largest goods exporter, China, is for global goods prices to FALL. Thereby, while Trump’s tariffs will be inflationary for the US they will be DEFLATIONARY for Europe. We go through the implications for rates, bonds, stocks, and FX. Plus: tactically underweight global utilities (JXI); and tactically buy TGT.