Latest from BCA Research
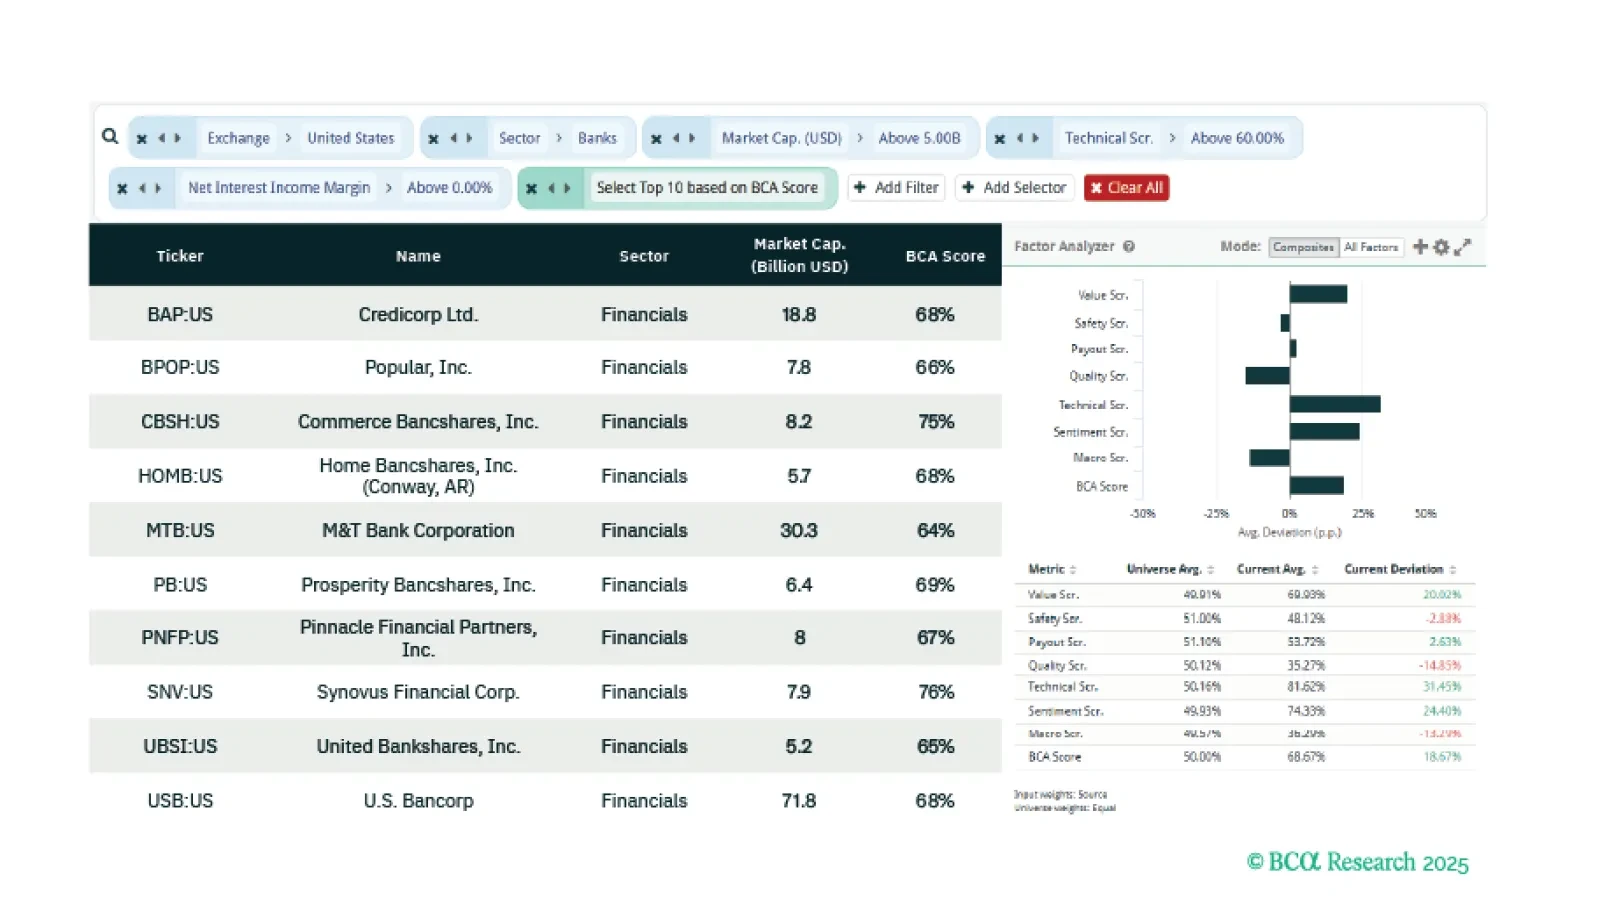
This week our three screeners identify: Equity plays on US banks, stocks that benefit from heightened US fiscal uncertainty, and a global Value and Technical basket of stocks.


Consensus sees one final ECB cut; we argue two are coming as deflationary forces are building in Europe. Dive in for the trade map: falling Bund yields, tighter peripheral spreads, and a euro primed for a 2026 rebound.

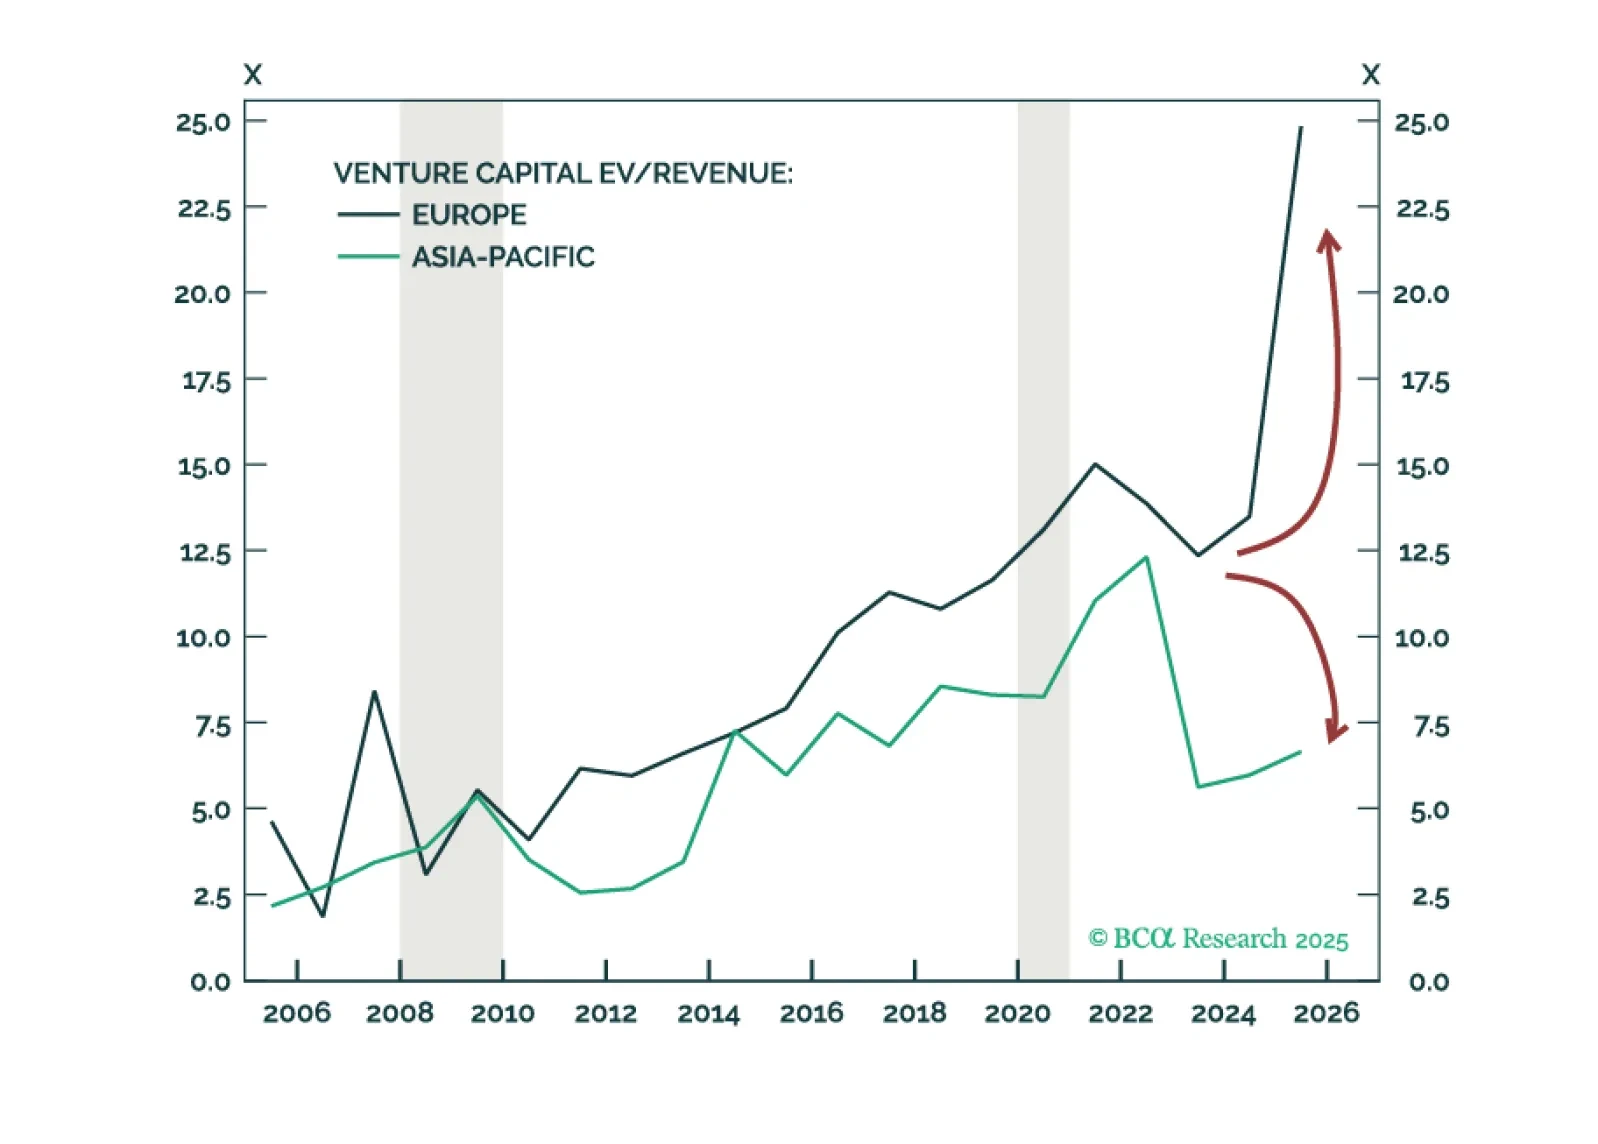
European euphoria is overdone. The most exceptional asset class in Europe is Infrastructure, but granular opportunities span other asset classes by sector and country. Venture Capital is a North America and Asia-Pacific play. We downgrade Private Credit, and upgrade Global Buyouts. Time to take profits on Long-Short Equity Hedge Funds.
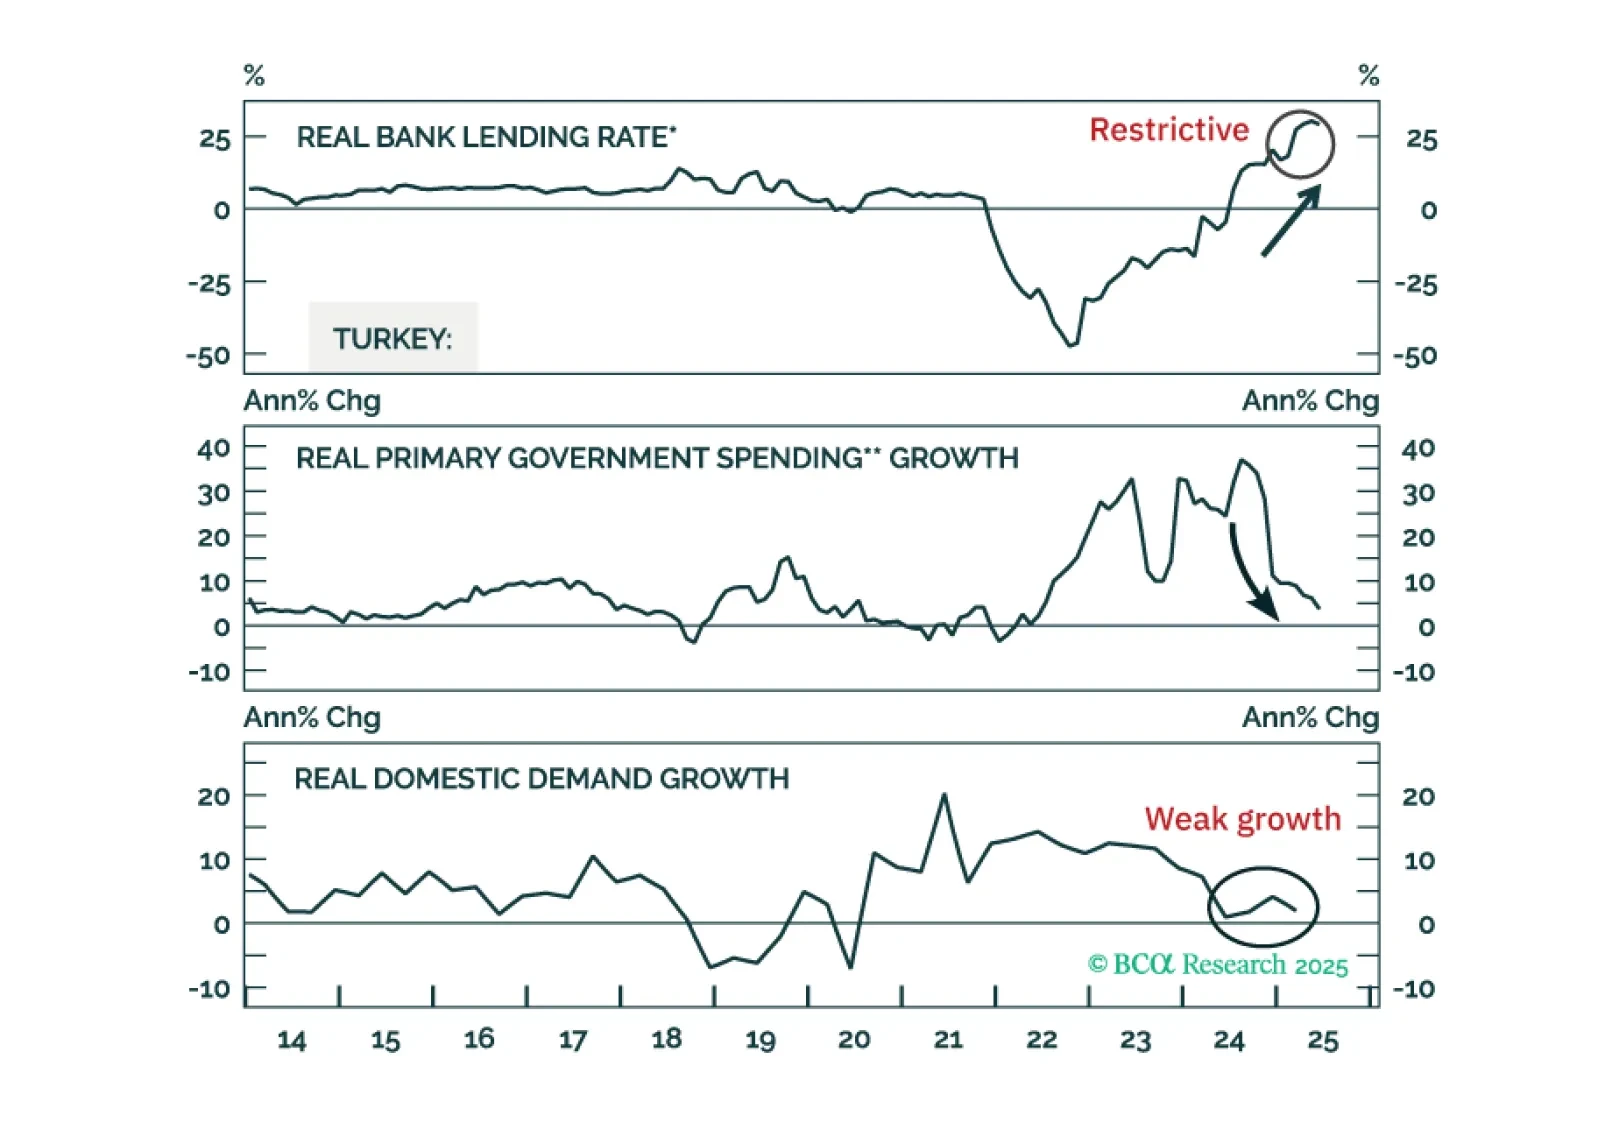
Thanks to the tight monetary and fiscal policies so far, inflation and growth are heading lower in Turkey. Buy 2-year local currency bonds, currency unhedged. Also, upgrade Turkey's domestic bonds from neutral to overweight and stocks from underweight to neutral within their respective EM portfolios.

U.S. copper tariffs will redirect the metal’s trade flows from the US to the rest of the world, replenishing depleted inventories abroad. With global copper demand set to soften in H2, the red metal will likely face downward price pressure outside the US. Stay long gold / short LME copper, and initiate an outright LME copper short.

Banks have had a strong run and may continue to outperform, supported by a rebound in capital market activity, improving momentum in the core banking business, and the potential for rerating driven by deregulation. While risks remain, we remain cautiously optimistic.
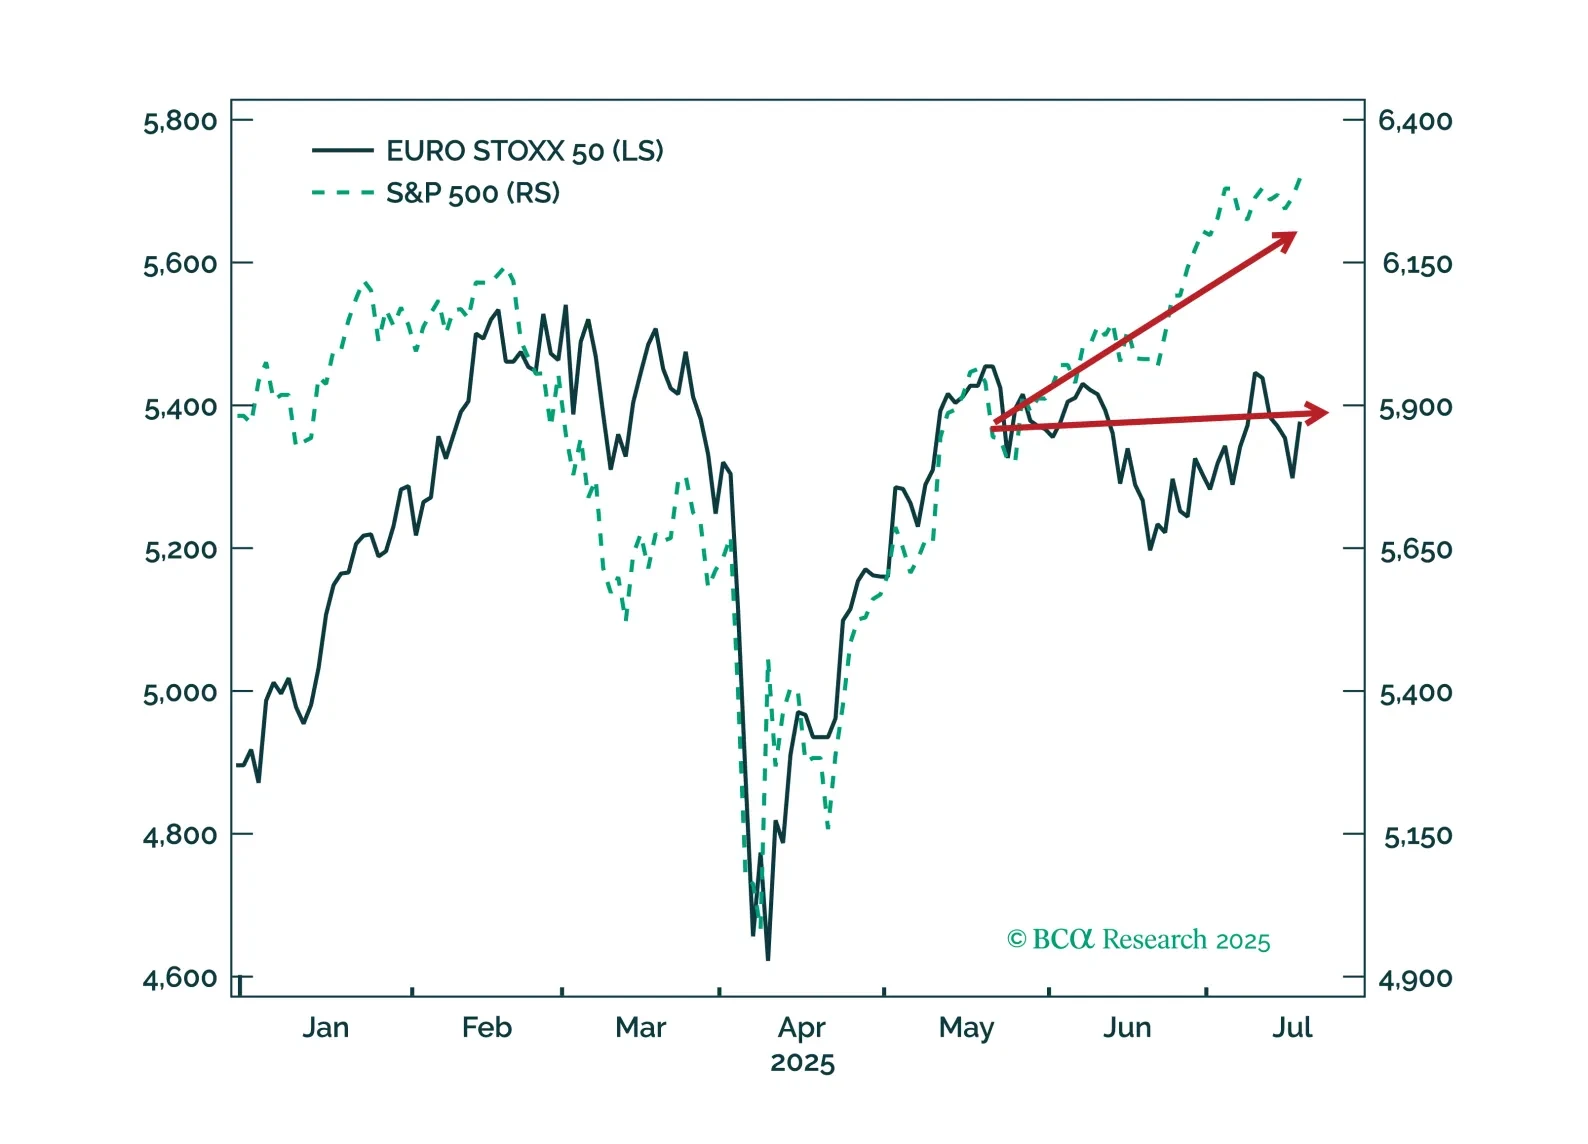
This insight gives life to four high-conviction views on European small caps, aero¬space & defense, banks, and telecoms by harnessing the power of BCA’s Equity Analyzer (EA).

EUR/JPY has reached stretched levels, prompting new short trade recommendations across BCA Strategies. The calls are underpinned by compelling valuation, macro, and technical signals.